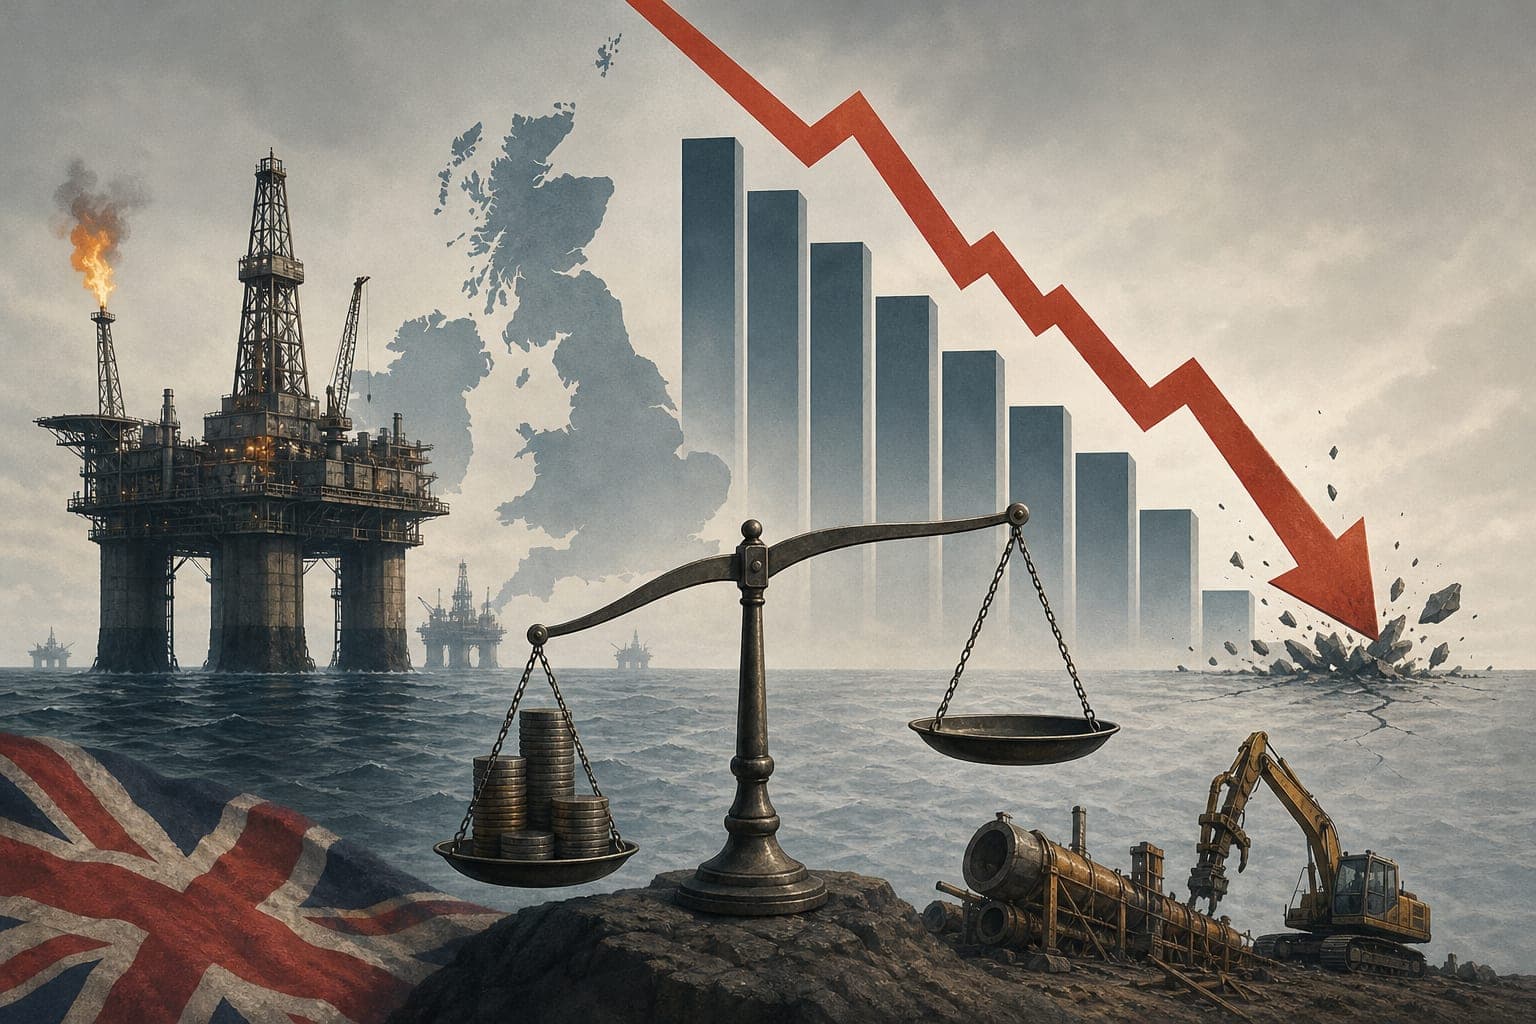
Seldom has a fiscal forecast carried such profound implications for national energy policy. According to the Office for Budget Responsibility's March 2026 projections, the United Kingdom's oil and gas tax revenues will decline from approximately four billion pounds in 2025–26 to a mere one hundred million by 2030–31. This represents a staggering 98% collapse within just five years. The precipitous decline stems from falling production volumes, weakening energy prices, and the anticipated expiry of the Energy Profits Levy. For a nation that once derived substantial treasury income from North Sea extraction, these projections signal the end of an era.
The geological reality underpinning these forecasts is stark. Approximately 90% of the North Sea basin has already been drilled out, and production has fallen by 77% since its peak around the year 2000. Exploration activity has virtually ceased, with zero offshore exploration wells drilled during the 2024–25 fiscal year. Moreover, upstream investment is contracting sharply, with a projected ten percent year-on-year reduction. Major operators, including BP, have announced their intention to divest entirely from the region.
Compounding these challenges is the escalating cost of decommissioning ageing infrastructure. The industry regulator estimates total decommissioning expenditure at roughly 43 billion pounds. Decommissioning spending reached a record 2.6 billion pounds in 2025 alone. Critically, the Exchequer must fund at least 11.7 billion pounds in tax relief for these operations. In some years, government decommissioning payouts have actually exceeded the oil and gas revenue collected.
The contrast with Norway's stewardship of its petroleum resources remains a salient point of comparison. Norway established a sovereign wealth fund in 1990, which now exceeds two trillion dollars. Britain, having extracted comparable volumes of hydrocarbons, never created an equivalent savings mechanism. Instead, successive governments channelled revenues into current expenditure, including tax reductions and public spending. Had Britain adopted a similar approach, estimates suggest the resulting fund could have been worth up to one trillion pounds.
What distinguishes this moment from previous downturns is the irreversible nature of the decline. New licensing cannot restore the North Sea as a lasting source of public revenue. Policymakers must therefore confront the imperative of accelerating the energy transition while managing the fiscal consequences of decommissioning. Critics warn that clean energy employment is not materialising at sufficient scale to offset job losses. The coming decade will reveal whether Britain can transform this structural challenge into an opportunity for economic renewal.