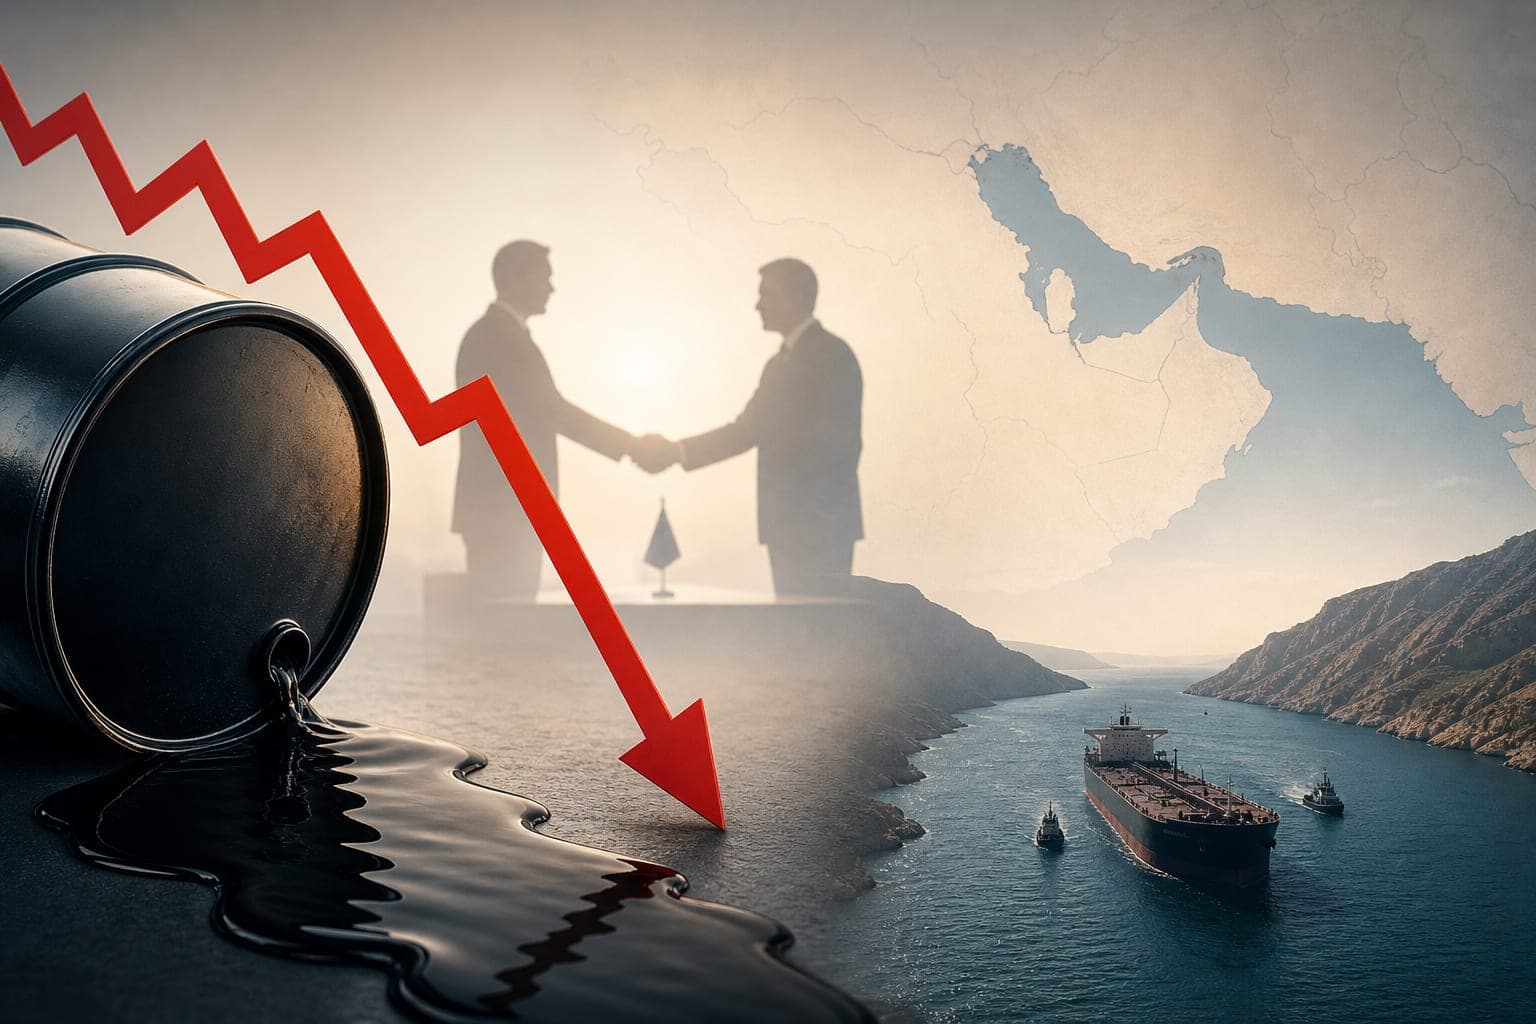
Seldom has a single diplomatic remark triggered such a dramatic repricing across global energy markets. Brent crude futures tumbled approximately 5% on Monday, falling to around $93 per barrel. This marked the benchmark's lowest level since early September. The precipitous decline followed President Trump's statement that fresh military strikes on Iran were 'highly unlikely.'
The sell-off extended an already historic downturn. Brent had plunged 16% the previous week, its steepest weekly drop since the pandemic-era collapse of 2020. Analysts at Saxo Bank noted that prices were declining on hopes of a peace deal rather than concrete diplomatic progress. Physical crude prices have also slipped below futures, signalling easing supply tightness in the near term.
The geopolitical backdrop remains inherently volatile, however. Attacks on shipping near the Strait of Hormuz have persisted despite the conciliatory rhetoric from Washington. Roughly a fifth of the world's seaborne crude oil transits through this critical waterway. Any sustained disruption there could swiftly reverse the current bearish momentum and reinstate a substantial risk premium.
Underlying market fundamentals have compounded the downward pressure on prices. JPMorgan estimated a global oil surplus of 1.4 million barrels per day in October. Meanwhile, OPEC+ has maintained its November production targets at 31 million barrels per day. The convergence of diplomatic optimism and excess supply has created a distinctly bearish market configuration.
Looking ahead, the trajectory of oil prices hinges on whether negotiations yield a durable resolution. Without a substantive agreement, markets remain vulnerable to sharp reversals should hostilities resume. For energy-dependent industries, this period of heightened uncertainty demands robust hedging strategies and scenario planning. Rarely has the interplay between geopolitics and commodity pricing been so consequential for corporate decision-making.