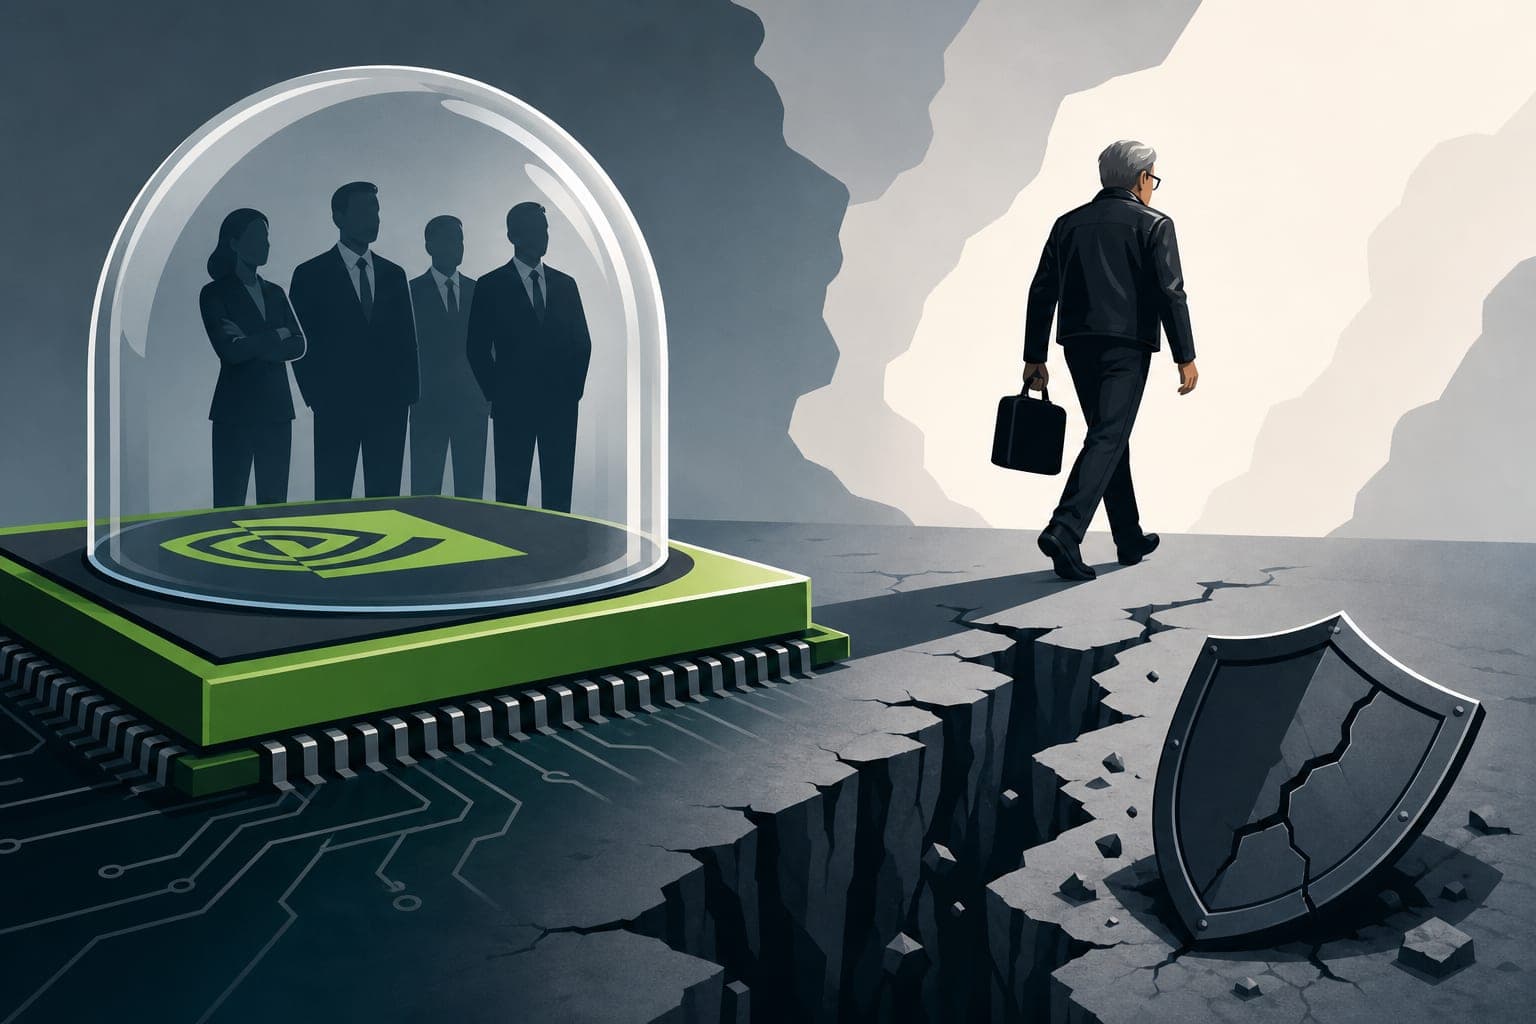
Seldom has a corporate leadership crisis so rapidly eroded shareholder value. Nvidia's co-founder Jensen Huang resigned as CEO on November 12, 2026, amid allegations of affairs with a suspected Chinese spy. The chipmaker's stock plunged as much as fourteen percent intraday, wiping out approximately six hundred billion dollars in market capitalization. This unprecedented single-session loss underscored the vulnerability inherent in Nvidia's dependence on one individual.
Compounding the crisis is a striking insurance gap now drawing intense scrutiny from analysts. Nvidia purchased up to nine hundred million dollars in directors and officers liability insurance through broker Aon. However, the policy covers only Side A, which shields executives' personal assets and legal defense costs. Side B, which reimburses the company for indemnifying executives, and Side C, which covers entity-level securities claims, were both omitted.
This omission is highly unusual among publicly traded firms of Nvidia's stature. A 2018 survey by insurance broker WTW found that over eighty percent of listed companies purchase Sides B and C. Legal experts have noted that large American corporations almost universally carry full coverage given their significant litigation exposure. Without such protection, Nvidia must absorb any corporate-level damages and defense expenses from its own balance sheet.
Shareholder lawsuits have already materialized. A proposed class action filed in federal court in San Jose accuses Nvidia of defrauding investors. The complaint alleges the company concealed Huang's ties with Alice Huang, a former Megaspeed executive described as a suspected intelligence asset. A separate derivative action, filed on the company's behalf, seeks redress for harm to Nvidia itself. Additional stock-drop litigation tied to the share price decline may follow.
The broader implications extend well beyond Nvidia's boardroom. This case illustrates how reputational risk concentrated in a single executive can cascade into existential financial exposure. Had Nvidia maintained comprehensive coverage, its balance sheet would have been partially insulated from such contingencies. For corporate governance practitioners, the lesson is unambiguous: robust insurance architecture is not merely prudent but indispensable.