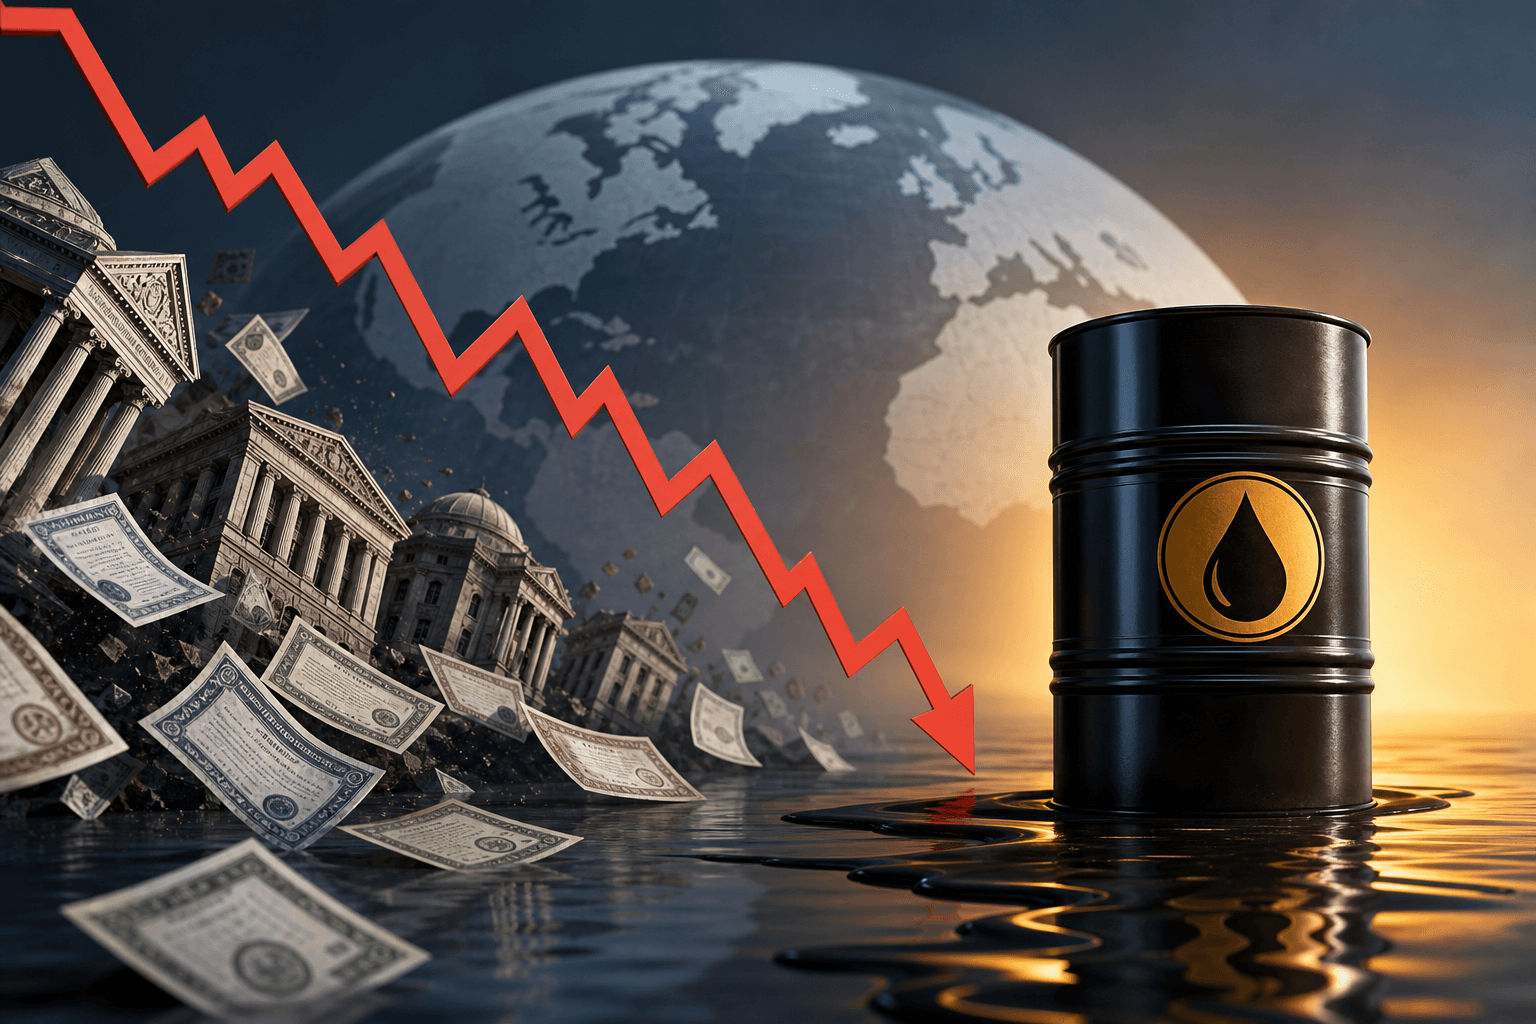
Seldom has the global bond market experienced such a pronounced and sustained rout. Government bond yields have surged to multi-decade highs across major economies. The sell-off has been fueled by persistently elevated oil prices and mounting fiscal concerns. Brent crude has remained above the $100 threshold, with futures recently settling near $106 per barrel. This confluence of factors has compelled investors to reassess their appetite for sovereign debt fundamentally.
The repercussions are strikingly broad in scope. The U.S. ten-year Treasury yield has climbed above five percent, reaching its highest level since 2007. Germany's benchmark ten-year yield has crossed 3.5 percent for the first time since 2011. Japan's ten-year yield has breached three percent, a level not witnessed since 1996. Yields have also risen sharply across the Asia-Pacific region, underscoring the global nature of this upheaval.
Several structural forces underpin this turbulence. Geopolitical tensions in the Middle East have disrupted energy supply chains, sustaining elevated oil prices. Hawkish central bank commentary has reinforced expectations of further monetary tightening. Traders now price a seventy-one percent probability of a Federal Reserve rate hike in October. The European Central Bank has likewise signaled a willingness to move rates into restrictive territory.
The fiscal ramifications are particularly acute for heavily indebted nations. Japan's government debt exceeds two hundred percent of gross domestic product, making its budget acutely sensitive to borrowing costs. U.S. national debt has surpassed forty trillion dollars, with interest payments exceeding one trillion annually. France has already cut its growth forecast to just 0.4 percent, citing inflation and a construction downturn. These deteriorating fiscal trajectories compound investor anxiety.
For businesses and consumers, the implications are far-reaching. Rising yields translate directly into higher mortgage rates, costlier corporate borrowing, and constrained capital expenditure. Companies with substantial refinancing needs or floating-rate obligations are especially vulnerable. Whether this sell-off marks a structural repricing or a transient dislocation remains the paramount question for market participants.