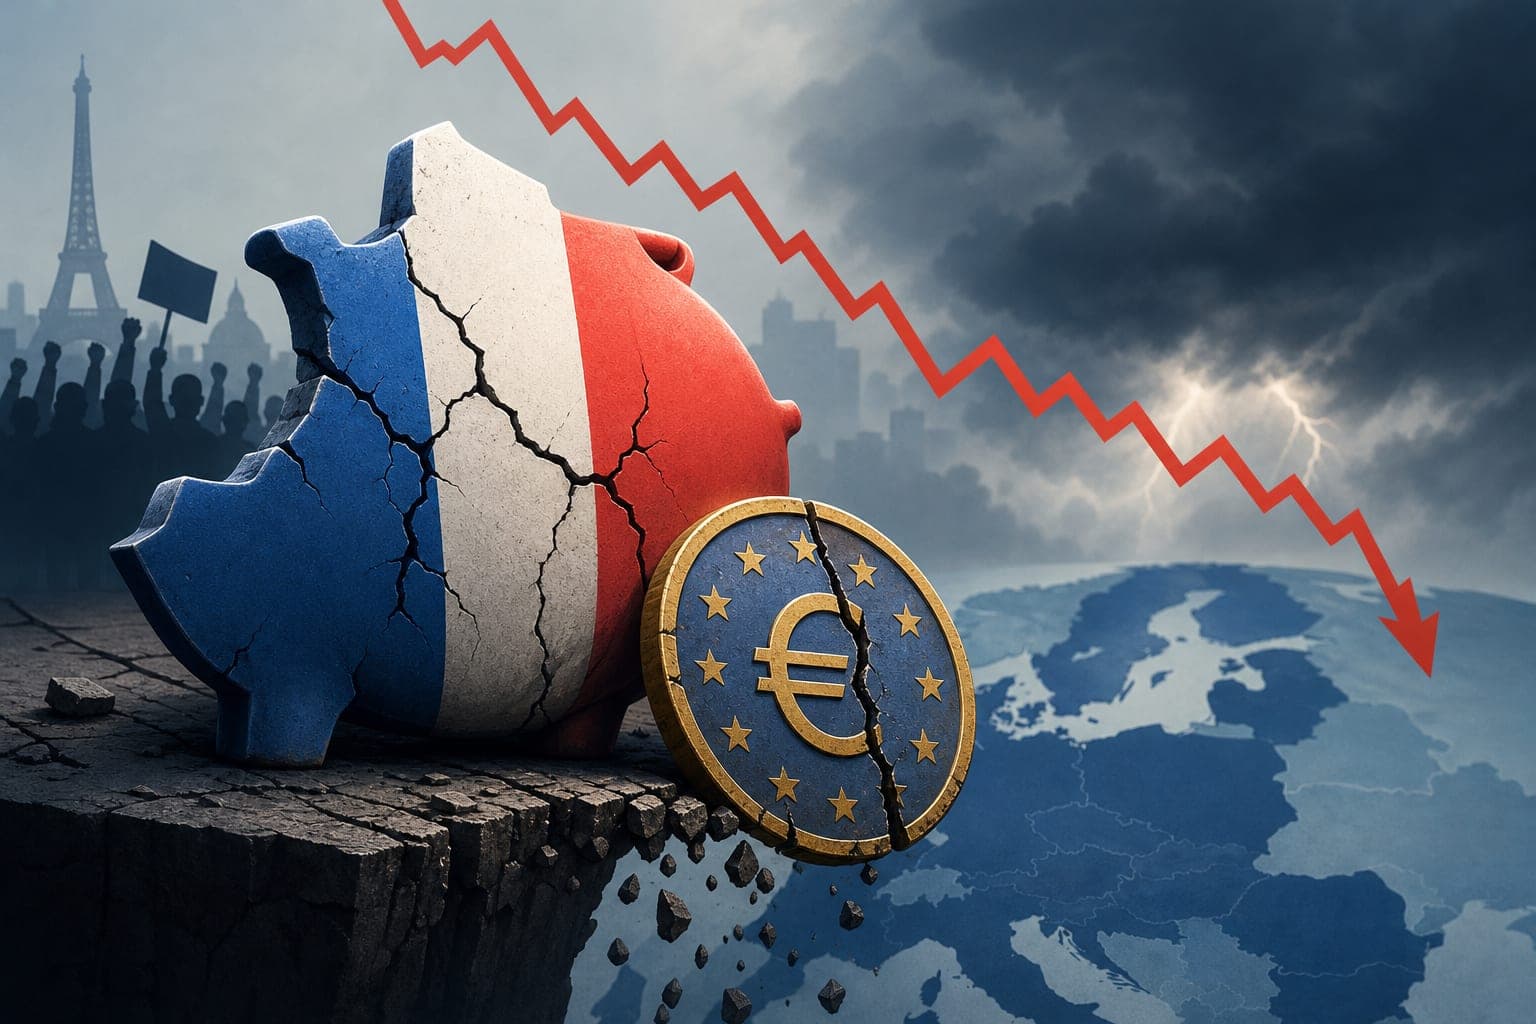
Seldom has social unrest so starkly illuminated a nation's underlying fiscal vulnerabilities. France's unprecedented wave of student protests has laid bare deep structural weaknesses in its public finances. What began as demonstrations over teacher shortages and deteriorating school infrastructure has evolved into a nationwide movement. The unrest now poses a significant threat to the government's ability to implement essential budgetary reforms.
The country's fiscal position is undeniably precarious. Public debt stood above $4 trillion in June, equivalent to 119% of GDP. The cost of servicing that debt has surged as bond yields have risen sharply. France's ten-year borrowing rate has climbed to nearly 5%, its highest level since 2002.
Markets have responded with considerable apprehension. The spread between French and German bond yields has widened to levels not seen since the eurozone debt crisis. Investors are now demanding substantially higher returns to hold French sovereign debt. The euro itself has fallen to a seventeen-month low against the dollar, reflecting broader concerns about fiscal contagion.
The government's proposed 2027 budget, targeting €54 billion in spending cuts and new revenue, has failed to reassure investors. Prime Minister Sébastien Lecornu lacks a parliamentary majority, complicating passage of austerity measures. With presidential elections looming in 2027, analysts fear fiscal populism may dilute any meaningful consolidation. The IMF has issued a stark warning, urging France to restore fiscal credibility without delay.
Beyond France, the spillover risks are substantial. Bond yields in Italy, Greece, and Belgium have also begun rising in tandem. Should France's crisis deepen, the ramifications for the eurozone's institutional framework could prove severe. What distinguishes this episode from previous crises is France's systemic importance as Europe's largest sovereign bond market.