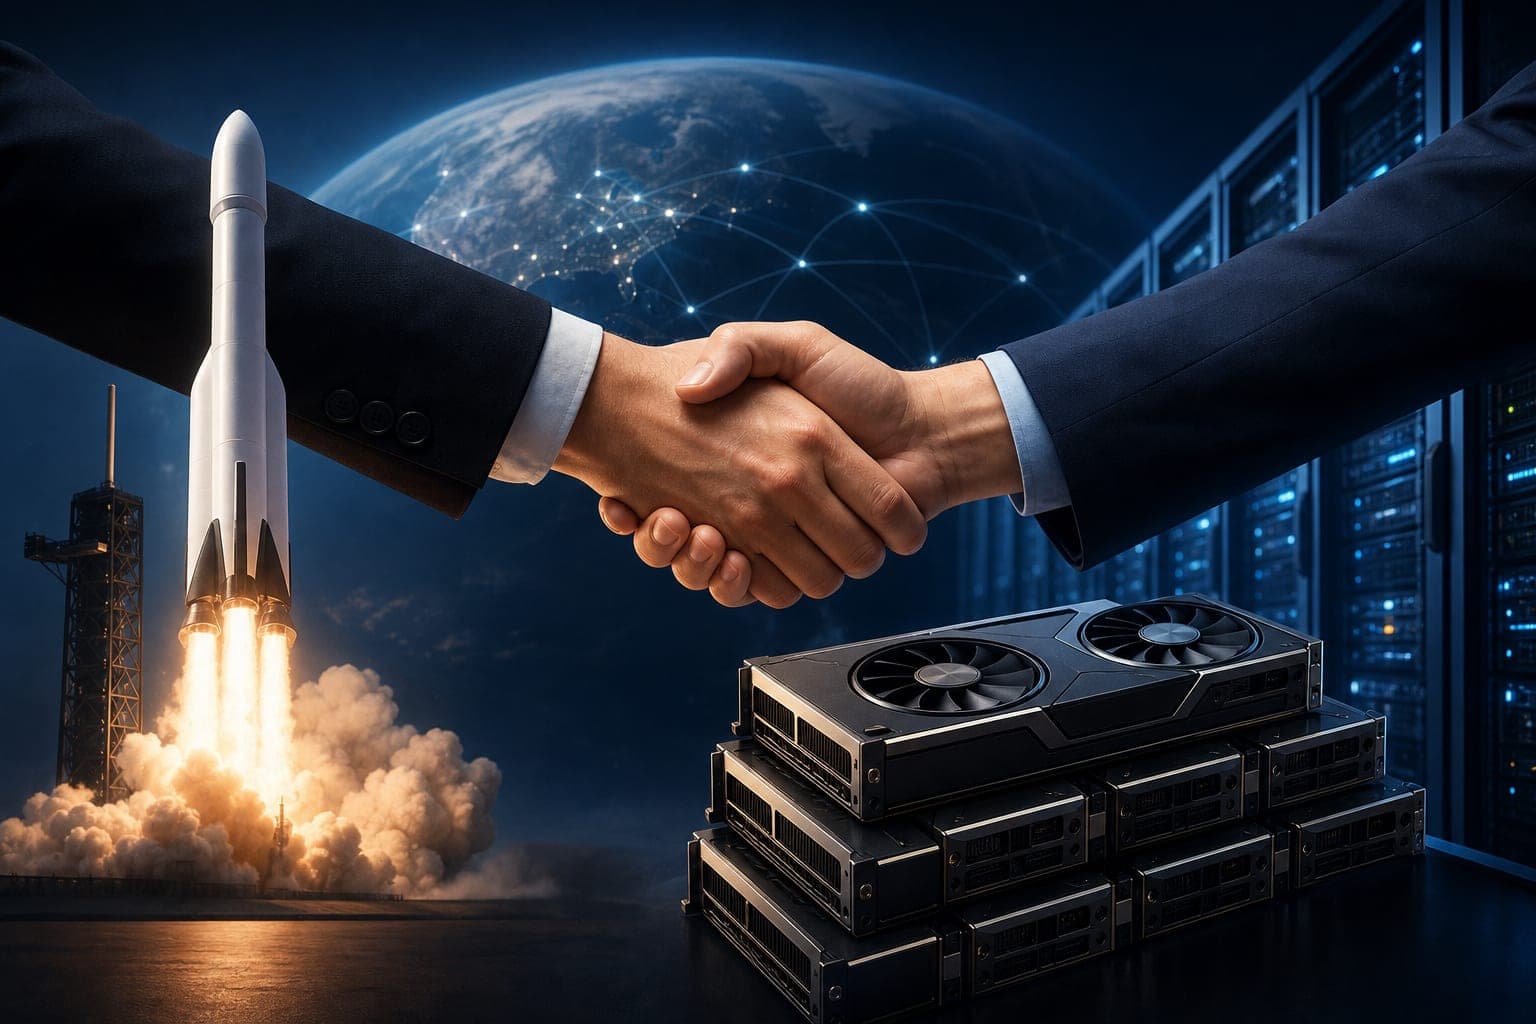
Seldom has a single financing announcement so starkly illustrated the capital intensity of the artificial intelligence race. Elon Musk declared that SpaceX has closed a $40 billion debt deal to procure Nvidia graphics processing units. The transaction, structured as an equipment-finance lease with Apollo Global Management, represents the largest committed GPU financing to date. Yet Bloomberg reported that pricing discussions were still ongoing when Musk made his announcement.
The deal's architecture reveals a sophisticated approach to corporate finance. Goldman Sachs led negotiations involving a special purpose vehicle designed to keep the debt off SpaceX's balance sheet. This off-balance-sheet structure preserves the company's investment-grade credit rating, a critical differentiator in tightening debt markets. Each lease will run approximately five years from the date of equipment delivery, with GPU shipments anticipated in the first half of 2027.
What distinguishes SpaceX from its competitors is its diversified revenue base. Musk emphasized that the company generates substantial income from both its Starlink satellite internet service and its rocket launch operations. SpaceX's AI segment alone brought in $7.6 billion in the third quarter, surpassing revenue from Starlink and launches combined. This diversification proved instrumental in securing favorable financing terms amid a broader credit contraction.
Musk's announcement carried an ominous warning for the broader AI infrastructure sector. He predicted that over 200 neocloud companies would face widespread failures and consolidation as debt markets tighten. These neoclouds, which lease computing capacity tailored to AI workloads, lack the diversified revenue streams that underpin SpaceX's creditworthiness. Musk dismissed the prospect of acquiring any struggling neoclouds, calling such a strategy pointless.
The implications of this deal extend well beyond SpaceX's corporate trajectory. It signals a widening bifurcation in AI financing, where investment-grade borrowers retain access to capital while single-revenue firms are squeezed out. Industry analysts note that debt-funded AI capital expenditure could rise to 40 percent of total spending by 2027. Whether this concentration of resources accelerates innovation or merely entrenches incumbents remains an open question.